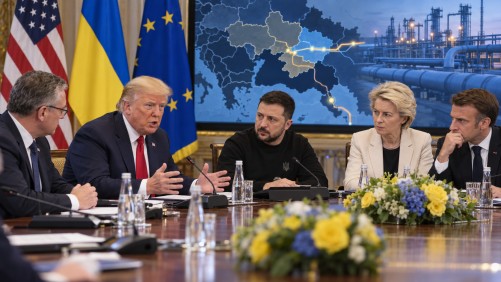
US President Donald Trump has signed an executive order easing sanctions on Russia’s energy sector, a decision that has sparked concerns over the United States’ commitment to Ukraine amid its ongoing conflict with Russia. The move comes after recent legislation allowed for tariffs of up to 100% on major buyers of Russian oil and gas, targeting Russia’s energy and defense industries.
The decision has heightened tensions between Washington and Kyiv, as Ukrainian President Volodymyr Zelensky continues to press European Union leaders for increased support. Following discussions in Brussels, Zelensky appealed for an additional €70 billion (approximately US$79 billion) in financial and military aid next year, emphasizing the need for more Patriot air defense missiles to counter Russian attacks.
Strains have emerged in the US-Ukraine relationship, particularly after Trump criticized Ukraine for launching renewed strikes on Russian oil refineries. Additionally, disruptions in satellite communications used by Ukrainian forces have raised concerns, although SpaceX CEO Elon Musk has denied his company’s involvement, and a US official refuted any intervention by Trump.
Despite these challenges, European leaders have reiterated their commitment to supporting Ukraine. European Council President António Costa has called for sustained assistance and increased pressure on Russia, while other EU officials consider Ukraine’s financial needs. The EU is already distributing funds from a €90 billion loan to support Ukraine through 2027, but Ukrainian authorities warn of a significant funding gap due to ongoing Russian attacks on its infrastructure.
In light of these developments, discussions have resurfaced about potentially using €200 billion in frozen Russian central bank assets to support Ukraine’s defense and recovery efforts. However, this proposal faces significant opposition, particularly from Belgium, where a majority of these assets are held.
